For many people, buying a home begins as a lifestyle decision. You want more space, a shorter commute, a backyard, better proximity to family, or simply a place that feels like your own.
But over time, real estate can become something else: a significant part of your financial foundation.
That is why buyers and homeowners often ask, "How does real estate build wealth?"
The simplest answer is that real estate can allow an owner to build equity in an appreciating asset over a long period of time. But the actual wealth-building equation is more nuanced. Mortgage principal reduction, leverage, appreciation, rental income, strategic improvements, and eventually using accumulated equity to purchase additional assets can all play a role.
In a market like Greater Seattle, where housing demand is influenced by employment, population, land constraints, neighborhood development, and the broader regional economy, long-term ownership has historically created meaningful opportunities for many homeowners and investors. That does not mean prices rise every year, nor does it mean every property is automatically a good investment.
Real estate is not a guaranteed path to wealth.
But when the right property is purchased at a sustainable cost and held with a long-term perspective, it can become a powerful financial tool.
Wealth Building Usually Starts With Equity
To understand how real estate creates wealth, start with equity.
Home equity is essentially the difference between a property's market value and the debt secured against it. If a home is worth $1 million and the remaining mortgage balance is $700,000, the homeowner has approximately $300,000 in gross equity before considering selling costs or other obligations.
Equity can grow in more than one way.
First, a portion of a typical amortizing mortgage payment goes toward reducing principal. In the early years of a mortgage, a larger portion of the payment generally goes toward interest, but over time more of each scheduled payment is typically applied to principal. As the loan balance declines, the homeowner's equity can increase even if the property's value remains unchanged.
The second component is appreciation. If the market value of the property increases over time, the owner's equity can grow from both directions: the debt becomes smaller while the asset becomes more valuable.
This combination is one of the fundamental reasons homeownership can become a long-term wealth-building mechanism.
It also explains why the most important period in real estate is often not the first year after purchasing. It is the fifth, tenth, or twentieth.
Appreciation Can Be Powerful, but It Should Not Be Assumed
Seattle homeowners have experienced periods of substantial appreciation over the past several decades, driven in part by employment growth, constrained land supply, regional desirability, and demand for housing.
But real estate does not move in a straight line.
Individual neighborhoods can outperform or underperform. Economic conditions change. Interest rates influence affordability. Employers expand and contract. New construction alters supply. Buyer preferences evolve.
Even within Greater Seattle, appreciation can look very different depending on the property.
A home in Seattle may behave differently from one in Bellevue. Redmond's employment base and housing mix create different dynamics from Kirkland's waterfront and close-in neighborhoods. Issaquah and Bothell each offer their own combination of schools, transportation, development, housing stock, and land availability.
This is why buyers should be cautious about purchasing a home based on the assumption that it will appreciate by a specific percentage every year.
A stronger investment thesis asks whether the property has characteristics likely to remain desirable over time.
Location, land, access to employment, transportation, schools where relevant to buyer demand, neighborhood amenities, functional floor plans, and scarcity can all contribute to long-term desirability.
Appreciation is most useful when treated as a potential result of owning a strong asset—not as a promise used to justify buying one.
Leverage Is What Makes Real Estate Financially Different
One of the most distinctive features of real estate investing is leverage.
When you purchase a home with a mortgage, you control an asset worth considerably more than the cash you initially contributed.
Consider a simplified example. Suppose a buyer purchases a $1 million property using $200,000 as a down payment and finances the remaining amount. If the property eventually appreciates to $1.1 million, that $100,000 increase is based on the value of the entire property, not merely the buyer's original $200,000 down payment.
That illustrates why leverage can magnify returns on the owner's invested capital.
But leverage works in both directions.
If property values decline, the owner still owes the mortgage. Transaction costs, interest, taxes, insurance, and maintenance also need to be considered when evaluating actual returns.
This is why "real estate always goes up" is not a serious investment strategy.
Leverage becomes most powerful when buyers purchase within their means, maintain adequate reserves, and have enough time to ride through normal market cycles.
The objective should not be to borrow the maximum amount a lender will approve. It should be to use financing in a way that supports your broader financial goals.
Your Primary Residence Can Build Wealth Without Feeling Like an Investment
Not every homeowner thinks of their primary residence as an investment property, and in many ways, they shouldn't.
Your home serves a practical and emotional purpose that a stock portfolio does not. You live there. You make memories there. You may choose renovations because you enjoy them rather than because they produce the highest possible return.
Yet a primary residence can still become one of the largest assets on a household balance sheet.
Instead of paying rent to a landlord, homeowners with amortizing mortgages generally build some equity as principal is repaid. Over a long ownership period, that combination of principal reduction and potential appreciation can create substantial value.
There is also a behavioral component that is easy to overlook.
For many households, a mortgage effectively creates a form of disciplined wealth accumulation. Owners do not need to consciously decide every month to invest in home equity; principal reduction occurs through the regular payment schedule.
That does not automatically make owning financially superior to renting. Renters can build significant wealth by investing the difference between renting and owning, and homeownership comes with expenses renters may not bear directly.
The right comparison is therefore not "rent is throwing money away."
It is whether the complete economics of ownership make sense for your finances, expected holding period, and lifestyle.
Time May Be the Most Important Ingredient
Real estate wealth is rarely built quickly.
Short ownership periods can be challenging because buying and selling a property involves meaningful transaction costs. Market conditions can also change significantly over a few years.
Longer ownership periods give homeowners more time for principal reduction, potential appreciation, and market cycles to work.
Consider two buyers purchasing similar properties. One plans to move again in eighteen months. The other expects to remain for ten years.
Even if they buy at exactly the same price, the financial implications can be very different.
The longer-term owner has more time to spread transaction costs across the holding period and potentially benefit from appreciation and mortgage amortization. The short-term buyer may be much more exposed to near-term market fluctuations.
This is why one of the first questions we encourage buyers to consider is not simply, "Can I afford this home?"
It is, "How long is this home likely to work for me?"
A property that can accommodate several stages of your life may have financial value beyond its current bedroom count or finishes.
Strategic Improvements Can Create Equity
Real estate also provides owners with something they generally do not have with publicly traded investments: the ability to influence the asset directly.
A homeowner can improve a property's condition, functionality, and desirability.
That does not mean every renovation creates profit. In fact, homeowners frequently overestimate how much buyers will pay for highly personalized improvements.
The strongest value-creation opportunities are often more strategic.
A poorly presented home purchased below the value of comparable renovated properties may offer room for thoughtful improvements. Updating a dated kitchen, improving an awkward layout, addressing deferred maintenance, creating functional living space, or improving curb appeal can potentially increase marketability and value.
For investors, the opportunity may extend further. Depending on zoning, permitting, economics, and the individual property, adding rentable space or improving an underutilized property can alter its income potential.
The key is to distinguish between spending money on a home and investing money into a home.
The first makes the property nicer. The second should have a clear rationale for how the improvement supports value, usability, income, or marketability.
Rental Properties Add Another Wealth-Building Engine
Investment real estate introduces a component that a primary residence typically does not have: income.
A rental property can potentially generate revenue while the owner builds equity and participates in long-term property appreciation. Over time, rents may also change while a fixed-rate mortgage's principal-and-interest payment remains more predictable, although taxes, insurance, maintenance, vacancies, management, and other expenses can increase.
The important word is potentially.
A property that rents for a large amount is not automatically a good investment.
Investors need to understand the complete financial picture: acquisition price, financing, expected rent, vacancy, repairs, capital expenditures, property management, taxes, insurance, utilities where applicable, and regulatory considerations.
In Seattle and surrounding communities, those calculations can vary significantly by location and property type. A Seattle condominium, Bellevue single-family home, Redmond townhome, Kirkland duplex, or Bothell property with additional living space may each produce a very different investment profile.
Good real estate investing begins with the numbers.
The property should make sense before appreciation is used to rescue the analysis.
Equity Can Become a Tool for the Next Opportunity
One of the ways real estate wealth can compound is when equity accumulated in one property eventually helps support another financial move.
A homeowner may sell and use proceeds toward a larger home. An investor may eventually access capital, subject to financing requirements and risk considerations, to acquire another property. Someone who purchased a starter home may later retain it as a rental while moving into a new primary residence if the finances support that strategy.
This is how a single purchase can sometimes become the foundation for a broader real estate portfolio.
But accumulated equity should not be confused with free money.
Borrowing against a property increases debt and can change monthly obligations. Selling involves transaction costs and potentially tax considerations. Converting a primary residence to a rental changes the economics and responsibilities of ownership.
Every step should therefore be evaluated independently.
Building wealth is not about accumulating the largest number of properties possible. It is about owning assets that support your financial objectives without exposing you to risks you cannot comfortably absorb.
Why the Property You Buy Matters More Than Simply "Buying Real Estate"
It is easy to talk about real estate as though every property behaves the same way.
They do not.
Two homes purchased for $1 million can produce dramatically different outcomes over ten years.
One may sit on a desirable lot in a neighborhood with constrained supply, strong buyer demand, and excellent access to employment and amenities. Another may have an awkward layout, significant future maintenance, poor location within its community, or characteristics that limit its future buyer pool.
The purchase price alone does not reveal which is the stronger asset.
This is where analytical real estate advice matters. Buyers should consider comparable sales, land value, neighborhood trajectory, property condition, future supply, rental potential where relevant, renovation possibilities, and likely resale demand.
In a market as diverse as Seattle and the Eastside, those considerations can vary block by block.
The home you love should work for your life.
Ideally, it should also make sense on paper.
What Does the 2026 Seattle Market Mean for Long-Term Buyers?
One of the challenges of buying real estate is that people naturally focus on what is happening right now.
Mortgage rates matter. Inventory matters. Competition matters. Economic uncertainty matters.
But long-term wealth is rarely determined by whether someone bought during the perfect month.
The more consequential questions are often whether the buyer purchased a quality asset, paid a rational price, chose sustainable financing, maintained adequate reserves, and held the property long enough for the strategy to work.
The Seattle housing market in 2026 has given buyers something that was difficult to find during the most competitive years: more room to evaluate.
Elevated inventory in parts of the market has created opportunities to compare properties more carefully and, in some situations, negotiate on price or terms. At the same time, well-priced homes in desirable locations can still attract significant competition.
For a long-term buyer, that environment can reward selectivity.
Instead of asking only, "Will this house be worth more next year?" consider asking, "Would I still be comfortable owning this property if the market were relatively flat for several years?"
If the investment thesis requires immediate appreciation to work, the margin for error may be too small.
How The Mezon Group Approaches Real Estate and Long-Term Wealth
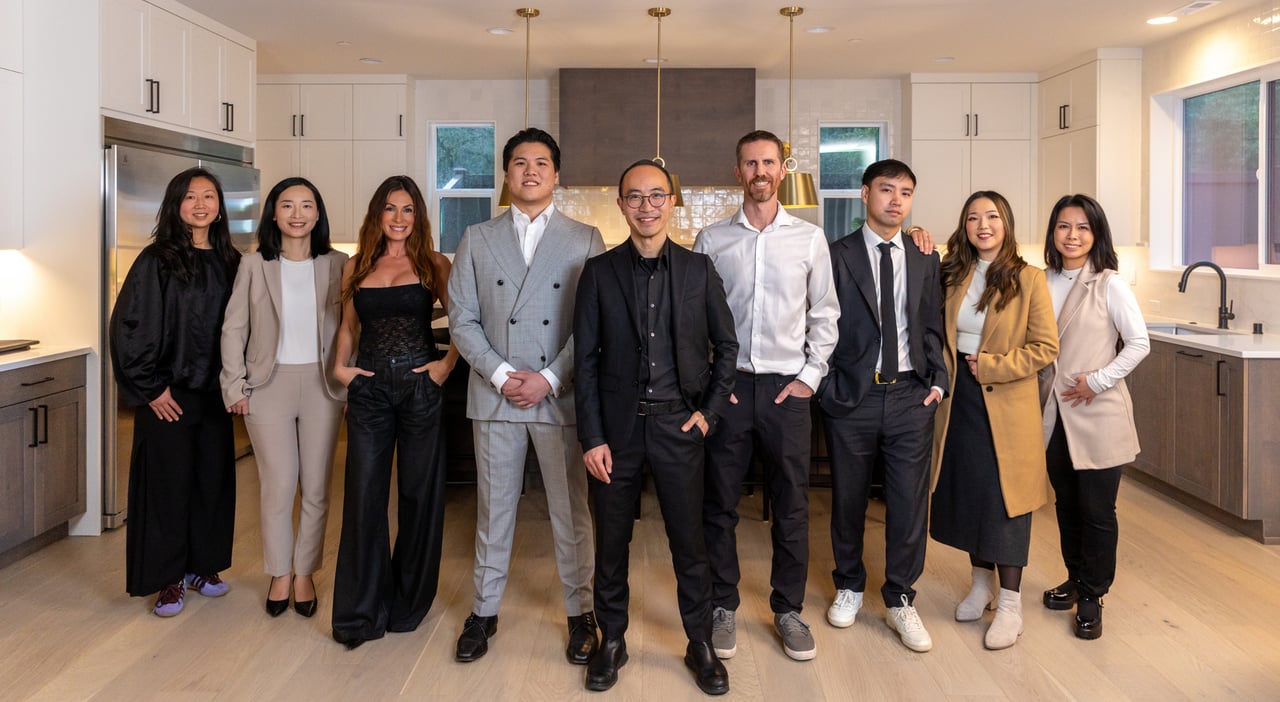
At The Mezon Group, our belief in real estate as a wealth-building tool comes from experience as well as our work representing clients.
Our founder, Kevin, has invested in real estate since 2015, including purchasing and renovating properties and operating Airbnb and furnished rentals. That experience influences how we approach real estate decisions today: not simply by asking whether a client can buy a property, but by helping them understand how that property fits into their broader goals.
Our team works with first-time buyers, homeowners, sellers, and investors throughout Seattle and Eastside communities including Bellevue, Redmond, Kirkland, Issaquah, and Bothell. We bring an analytical approach to comparable sales, property condition, potential returns, market positioning, and long-term resale considerations while recognizing that a home is never just a spreadsheet.
That approach has contributed to meaningful milestones for our team. In our first year as The Mezon Group, we were honored to be ranked #28 in Washington by sales volume among RealTrends Verified medium teams. [Read more about The Mezon Group's RealTrends Verified recognition →] https://www.realtrends.com/ranking/best-real-estate-agents-united-states/
By the halfway point of 2026, The Mezon Group had also guided 51 closed and pending transactions representing more than $48 million in sales volume across Seattle, Bellevue, Kirkland, Bothell, Redmond, Lynnwood, Renton, West Seattle, and communities throughout Greater Seattle.
We're grateful for those milestones, but they are not the reason we believe in real estate. What continues to motivate our work is seeing what the right real estate decision can make possible over time, whether that means purchasing a first home, creating stability for a family, acquiring an investment property, or building a portfolio over many years.
It is part of the philosophy behind our founder's motto: transforming lives one at a time.
Real Estate Is Personal. Your Wealth Strategy Should Be Too.
There is no universal timeline for building wealth through real estate.
For one person, the right strategy may be purchasing a first home and staying there for a decade. For another, it may mean buying a property with renovation potential. Someone else may eventually build a portfolio of rental properties.
The right strategy depends on income, liquidity, risk tolerance, lifestyle, time horizon, and financial goals.
If you're evaluating a home or investment property in Seattle, Bellevue, Redmond, Kirkland, Issaquah, Bothell, or elsewhere in Greater Seattle, we're always happy to help you think through the real estate side of the equation and understand how a particular property could fit into your longer-term plans.
Related Resources
Renting vs. Buying in Seattle: 2026 Math Breakdown
Compare the financial considerations behind renting and owning, including monthly costs, equity, flexibility, and expected holding period.
How Much Cash Do I Really Need to Buy a Home?
Understand the down payment, closing costs, reserves, and other upfront expenses to consider before purchasing.
The Bottom Line
So, how does real estate build wealth?
Usually, it does not happen because someone perfectly predicts the market or finds a property that doubles in value overnight.
It happens gradually.
Mortgage principal is paid down. Equity accumulates. A quality property may appreciate over time. Strategic improvements can create additional value. An investment property may produce income. And, eventually, the equity created through one property can sometimes help open the door to another opportunity.
That process can be particularly powerful because real estate combines something deeply personal—a place to live—with an asset that can play a meaningful role in a household's long-term financial life.
But successful real estate wealth building requires discipline. Buy thoughtfully. Understand the numbers. Avoid relying on appreciation alone. Maintain adequate reserves. Think beyond today's market. And give the strategy enough time to work.
The goal is not simply to own real estate.
It is to own the right real estate, for the right reasons, for long enough to let it become something more.