Seattle is an expensive place to buy a home. For some buyers, however, the question is not simply how to afford the monthly payment. It is whether the property itself can help offset some of that cost.
That is the basic idea behind house hacking.
If you're wondering, "What is house hacking?", it generally means purchasing a home as your primary residence while using part of the property to generate rental income. That might mean buying a duplex and living in one unit while renting the other, purchasing a home with an accessory dwelling unit, renting individual bedrooms, or choosing a property with a layout that can support a separate living space.
The concept has become particularly relevant in higher-cost housing markets such as Seattle and the Eastside. In communities like Bellevue, Redmond, Kirkland, Issaquah, and Bothell, even buyers with strong incomes can face substantial monthly housing costs. The ability to generate income from part of a property can potentially change the economics of ownership.
But house hacking is not free housing, nor is every property with an extra bedroom automatically a good investment.
Done well, house hacking can help reduce your effective housing costs, accelerate equity building, and potentially become the first step toward owning investment property. Done poorly, it can leave you paying a premium for a property that produces less income than expected while adding the responsibilities of being a landlord.
The question, then, is not simply whether house hacking works.
It is whether the numbers, the property, and the lifestyle work for you.
What Is House Hacking?
At its simplest, house hacking combines your primary residence with an income-producing component.
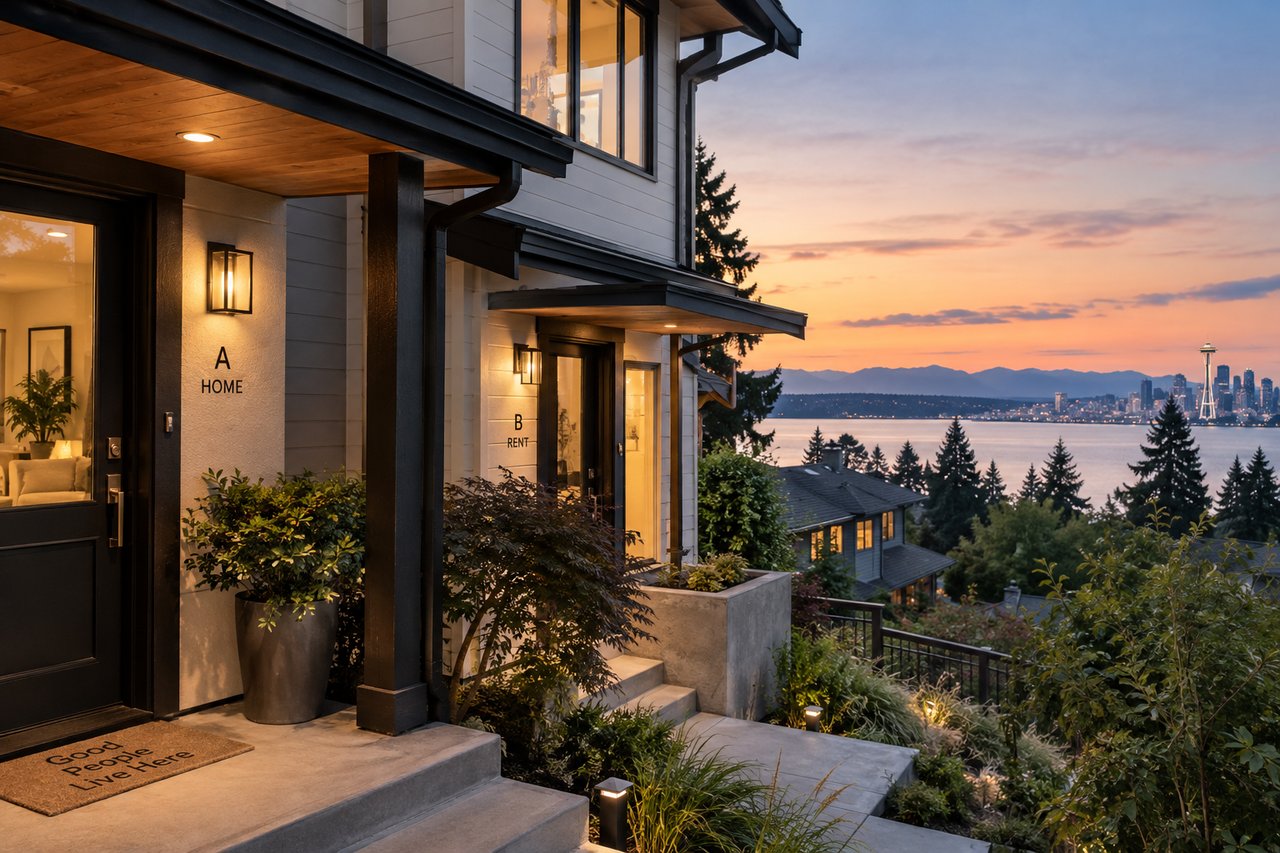
Imagine purchasing a duplex in Seattle. You live in one unit and rent the other. Instead of carrying the entire mortgage payment from your income alone, rent from the second unit helps offset part of the property's monthly cost.
The same concept can work with other types of homes.
A buyer might purchase a single-family home with a permitted accessory dwelling unit, commonly called an ADU. Another buyer might choose a property with a detached accessory dwelling unit, or DADU. Someone else may purchase a larger home and rent bedrooms to roommates.
The structure can vary considerably, but the principle remains the same: you live in the property while part of the property produces income.
That makes house hacking different from purchasing a traditional investment property where the owner lives somewhere else. Because the property is also your primary residence, financing, occupancy requirements, insurance, taxes, and other considerations may differ depending on the specific transaction and loan program.
This combination of homeownership and investing is exactly what makes house hacking attractive to many first-time buyers.
Why House Hacking Can Be Powerful in a High-Cost Market
The biggest advantage of house hacking is straightforward: rental income may reduce your effective monthly housing expense.
Suppose your total monthly housing cost is $5,500 and a separate portion of the property generates $2,000 per month in rent. Before accounting for taxes on rental income, vacancies, repairs, utilities, maintenance, and other expenses, your household is effectively carrying considerably less of the property's cost from employment income alone.
Over several years, that difference can become meaningful.
Instead of directing the full housing payment toward your residence every month, another occupant is contributing toward the economics of an asset you own. Meanwhile, if you have an amortizing mortgage, a portion of your mortgage payments generally reduces principal over time.
This is where house hacking can become a wealth-building strategy rather than simply a way to lower housing costs.
If the property also appreciates over the long term, the owner may benefit from a combination of principal reduction, potential appreciation, and rental income.
None of those outcomes should be taken for granted. But when the numbers work conservatively, they can create a compelling financial structure.
The Best House Hack Often Starts With the Property, Not the Rent
One mistake buyers make is beginning with a target rental income and then trying to force a property to fit the strategy.
A better approach is to evaluate the property itself.
Does the layout actually support privacy for both the owner and tenant? Is there a separate entrance? Are there enough bathrooms? How is parking handled? Would occupants share laundry? Are utilities separately metered, or would the owner need to determine how shared expenses are allocated?
These details can dramatically affect both rental desirability and your daily experience living in the home.
A basement with a kitchenette may look like an obvious rental opportunity during a showing, but buyers need to understand whether the space is legally permitted for the intended use. Similarly, an attractive detached structure in the backyard should not automatically be treated as a legal rental unit without appropriate due diligence.
In Seattle and surrounding cities, zoning, permitting, occupancy requirements, short-term rental regulations, and local landlord-tenant rules can all influence what is possible.
The strongest house hack is therefore not simply the property with the most potential rent.
It is the property where the physical layout, legal use, financing, and lifestyle all align.
Run the Numbers Conservatively
House hacking becomes dangerous when buyers make optimistic assumptions.
A property might look affordable if you assume the rental unit will generate $2,500 every month of the year. But what happens if the realistic rent is $2,200? What if it sits vacant for a month between tenants? What if an appliance fails or the unit needs repairs before it can be rented again?
The analysis should have room for reality.
Start with the property's full monthly ownership cost. That generally means looking beyond principal and interest to consider property taxes, homeowners insurance, applicable mortgage insurance, HOA dues where relevant, utilities paid by the owner, and expected maintenance.
Then evaluate rental income based on realistic comparable rentals rather than the highest listing you can find online.
A prudent analysis should also account for vacancy and repairs. Even when you live in the property yourself, the income-producing portion is still an operating asset with expenses.
The most important test may be this: Would you still feel comfortable owning the property if the rental income were lower than expected for a period of time?
If the entire financial plan collapses because the tenant moves out for six weeks, the margin for error may be too small.
Financing Can Be One of House Hacking's Biggest Advantages
One reason house hacking receives so much attention among first-time investors is that an owner-occupied property may offer financing options that differ from those available for a traditional non-owner-occupied investment property.
The exact down payment, qualification standards, treatment of potential rental income, and occupancy requirements depend on the borrower, property type, and loan program. Buyers should discuss those details directly with a qualified lender before assuming a particular strategy will work.
This becomes especially important with duplexes, triplexes, four-unit properties, ADUs, and other configurations where projected rental income may be part of the financial analysis.
A lender may not treat every dollar of projected rent as qualifying income, and documentation requirements can vary.
This is why financing should be explored before the home search becomes too narrow.
A buyer who understands the loan structure early can evaluate properties based on what is actually financeable rather than falling in love with an investment concept that does not fit the available financing.
House Hacking Is Also a Lifestyle Decision
The spreadsheet is only half the story.
Imagine purchasing your first home and then realizing your tenant lives directly below your bedroom. Or sharing a kitchen with roommates for several years because doing so produces the strongest financial return.
That may be perfectly comfortable for one buyer and completely unacceptable to another.
Privacy matters. Noise matters. Parking matters. Shared outdoor space matters. So does the responsibility of managing a tenant who may live only a few feet away.
House hacking works best when buyers are realistic about how much inconvenience they are willing to accept in exchange for financial benefit.
Some buyers prefer maximum separation and specifically search for duplexes or homes with detached ADUs. Others are comfortable renting individual bedrooms because the economics are stronger. A family may want a separate unit that can initially produce rental income but eventually accommodate parents or relatives.
There is no single ideal configuration.
The right house hack is one you can actually enjoy living in.
Location Matters Twice When You Are House Hacking
Location always matters in real estate, but a house hacker needs to think about location from two perspectives.
First, would you want to live there?
Second, would a tenant want to live there?
Those questions do not always produce the same answer.
A property may offer plenty of space but be inconvenient for renters because of limited transit, employment access, or amenities. Another property may be smaller but sit near major employers, light rail, universities, hospitals, restaurants, or other demand drivers that support a stronger rental market.
This is particularly relevant across Greater Seattle.
A Seattle property near transit may appeal to renters who want an urban lifestyle without relying heavily on a car. Redmond and Bellevue properties may benefit from proximity to major employment centers. Kirkland offers its own combination of employment access, waterfront amenities, and neighborhood appeal, while Issaquah and Bothell can provide different combinations of space, newer housing, commuting access, and rental demand.
For house hackers, neighborhood selection should therefore consider both resale demand and rental demand.
Ideally, you want a property future buyers will value even if you eventually stop renting part of it.
House Hacking Is Not Passive Income
The phrase "rental income" can make owning property sound remarkably easy.
The reality is more operational.
Someone needs to market the space, screen tenants in compliance with applicable laws, prepare and administer the rental arrangement, collect rent, respond to maintenance requests, coordinate repairs, maintain records, and understand applicable landlord-tenant requirements.
When the landlord lives on the same property, boundaries become especially important.
This does not mean house hacking is overly complicated. Many owners manage these responsibilities successfully. But buyers should enter the strategy understanding that they are taking on two roles: homeowner and housing provider.
Washington and local jurisdictions can also have detailed rules governing rental housing. Seattle in particular has significant landlord-tenant regulation, and requirements can change over time.
Before renting any portion of a property, owners should confirm current requirements with the appropriate government agencies and qualified legal or tax professionals when necessary.
Being a good investor starts with being a responsible housing provider.
Think About What Happens When You Eventually Move
One of the most interesting aspects of house hacking is what it can become later.
A buyer may live in the property for several years while renting part of it and eventually move elsewhere. Depending on financing, economics, regulations, and personal circumstances, the original home might then become a more traditional rental property.
That can potentially turn a first home into the beginning of a real estate portfolio.
But this should not be assumed from the beginning.
Before purchasing, consider whether the property would still make sense if you were no longer living there. Would the entire home rent effectively? Would the income support the expenses? Would managing multiple tenants make sense? Would selling and redeploying the equity be a better option?
A property that works beautifully as an owner-occupied house hack may not necessarily be an excellent standalone rental.
The strongest purchases give you options.
If the property works as your home today, has credible income potential while you live there, and retains strong resale appeal later, you have multiple paths available as your life changes.
What Are the Biggest Risks?
House hacking can improve the economics of homeownership, but it does not eliminate risk.
Rental income can fluctuate. Tenants can move. Repairs happen. Property values can decline. Interest rates and financing conditions can change. Local regulations can affect how a property may be rented.
There is also concentration risk. A significant portion of your savings may be tied to one property in one location while your home and investment are effectively the same asset.
That is why reserves matter.
If purchasing the home uses virtually every dollar you have available, relying immediately on rental income to cover the mortgage can create financial pressure. A stronger strategy leaves room for vacancies, repairs, and unexpected expenses.
House hacking should ideally create more financial flexibility over time, not less.
Is House Hacking Worth It in Seattle in 2026?
For the right buyer and property, it can be.
House hacking can be particularly compelling for buyers who want to own real estate but are comfortable trading some privacy or convenience for improved financial economics. It may allow someone to purchase a better-located or more flexible property while reducing the portion of the monthly housing cost they need to carry personally.
It can also provide hands-on experience with real estate investing before purchasing a completely separate investment property.
But it is not automatically better than simply buying a conventional primary residence.
A buyer should not pay an excessive premium for a mediocre property simply because it has a theoretical rental unit. Nor should projected rental income be used to justify stretching beyond a comfortable financial position.
The best house hack should still be a home you are comfortable owning if market conditions, rental income, or your personal plans change.
That is especially important in a market like Seattle, where the long-term quality of the underlying real estate matters.
How The Mezon Group Helps
At The Mezon Group, we believe real estate can be more than a transaction. It can be a tool for creating stability, flexibility, and long-term wealth when approached thoughtfully.
Our experience working with homeowners and investors shapes how we evaluate opportunities like house hacking. Rather than focusing only on whether a property has rental potential, we help clients think through the complete picture: purchase price, comparable sales, property condition, realistic rental assumptions, location, future resale demand, and how the home fits into their broader goals.
Our approach is analytical and strategic, but also personal. Whether you're considering your first home, a house hack, or a longer-term investment strategy in Seattle, Bellevue, Redmond, Kirkland, Issaquah, Bothell, or elsewhere in Greater Seattle, our goal is to give you the information and perspective needed to make the decision with confidence.
Real Estate Is Personal. The Numbers Should Still Work.
House hacking sits at an interesting intersection between lifestyle and investing.
You are choosing where you will live, but you are also evaluating an income-producing asset. That means the home needs to make sense emotionally and financially.
If you're exploring house hacking in Greater Seattle, we can help you evaluate potential properties from both perspectives and understand the questions worth answering before you make an offer.
Related Resources
How Real Estate Builds Long-Term Wealth in Seattle
Explore how equity, mortgage principal reduction, appreciation, leverage, rental income, and time can work together as part of a long-term real estate strategy.
How to Buy a Home With Friends or Family
Learn how combining resources can create another path toward homeownership, along with the financial, legal, and practical considerations involved.
The True Cost of Buying a Home in Washington State
Understand the expenses beyond the purchase price, including closing costs, ongoing ownership expenses, maintenance, and reserves.
The Bottom Line
So, what is house hacking, and is it worth it in Seattle?
At its core, house hacking means using part of the home you live in to generate income. That income can potentially reduce your effective housing cost, help you build equity while someone else contributes toward the property's economics, and provide an entry point into real estate investing.
But the strategy works only when the fundamentals work.
The property needs to support the intended use. The rental assumptions need to be realistic. The financing needs to make sense. You need sufficient reserves for vacancies and repairs. And perhaps most importantly, you need to be comfortable with the lifestyle that comes with sharing your property with tenants.
The strongest house hacks are not necessarily the properties producing the highest theoretical rent. They are homes that give their owners flexibility.
A good house hack works as a place to live today, an income-producing asset while you own it, and a property that another buyer may still want when it is eventually time to sell.
That is where house hacking can become more than a way to make a mortgage payment easier.
It can become the first step in a much longer real estate strategy.